OZ 2.0 — 2027 & Beyond
The One Big Beautiful Bill Act (OBBBA, P.L. 119-21) was signed by President Trump on July 4, 2025. Here is what that means for Opportunity Zones and investors looking for tax-advantaged investment opportunities.
OZ Becomes a Permanent Fixture
The OBBBA makes the Opportunity Zone program — “OZ 2.0” — a permanent component of the tax code beginning in 2027. OZ 1.0 still sunsets at the end of 2026, closing the window on the original program’s fixed deadline structure for good.
New 10-Year Zone Cycles Begin in 2027
All currently designated zones will remain active until December 31, 2028. Additionally, starting January 1, 2027, governors can redesignate new zones every ten years, with the next cycle running from 2027 to 2037.
What’s New for Investors
Investors with capital gains from 2026 and thereafter may invest into a “2.0” Qualified Opportunity Zone Fund (QOF). The program preserves the most powerful benefits from OZ 1.0 and adds meaningful new advantages:
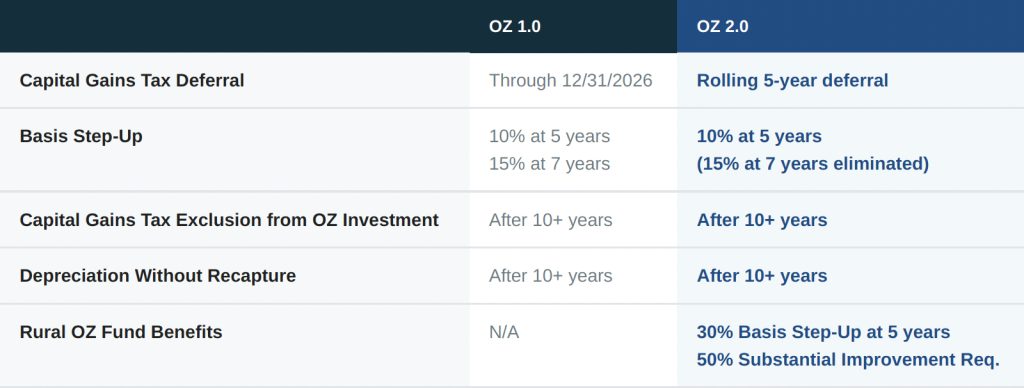
- Rolling 5-year deferral — gains invested on or after January 1, 2027 now defer tax for a full 5 years from the date of investment, regardless of when in the year the investment is made. This replaces the old fixed 12/31/2026 deadline and restores the runway that early 2018 investors received.
- 10% basis step-up on the deferred gain after 5 years, reducing the taxable amount at recognition. For investments in Rural OZ Funds, this step-up increases to 30%.
- Reduced substantial improvement threshold for Rural OZ properties — 50% of the property’s adjusted basis, down from 100% for Urban OZ Funds.
What Carries Forward from OZ 1.0
- Tax-free appreciation — all gains above the original investment are completely excluded from federal income tax if the QOF interest is held for 10+ years. This remains the most powerful structural advantage of OZ investing.
- No depreciation recapture at exit — OZ investors who hold for 10+ years pay zero depreciation recapture on exit, which in conventional real estate can represent a meaningful additional tax at 25%.
- Use of depreciation deductions during the holding period to offset income, further enhancing after-tax returns throughout the hold.
Why this matters for investors. The OBBBA transforms Opportunity Zones from a temporary tax incentive into a permanent, rolling tax-smart solution — giving investors more time, more certainty, and better economics to defer and potentially eliminate their capital gains tax liabilities.
OZ 1.0 vs. 2.0: What Changed for Investors